Two charts show how far homeownership is slipping out of reach as mortgage rates skyrocket
The Good Brigade/Getty Images
- Higher mortgage rates are making it tougher for people to move or achieve homeownership.
- The Atlanta Fed examines the income required for homeownership to cost no more than 30% of income.
- The analysis showed that’s now well above the actual median household income.
A few years ago, Americans were able to check off their goal of becoming homeowners thanks to historically low mortgage rates. It’s harder to achieve that dream these days.
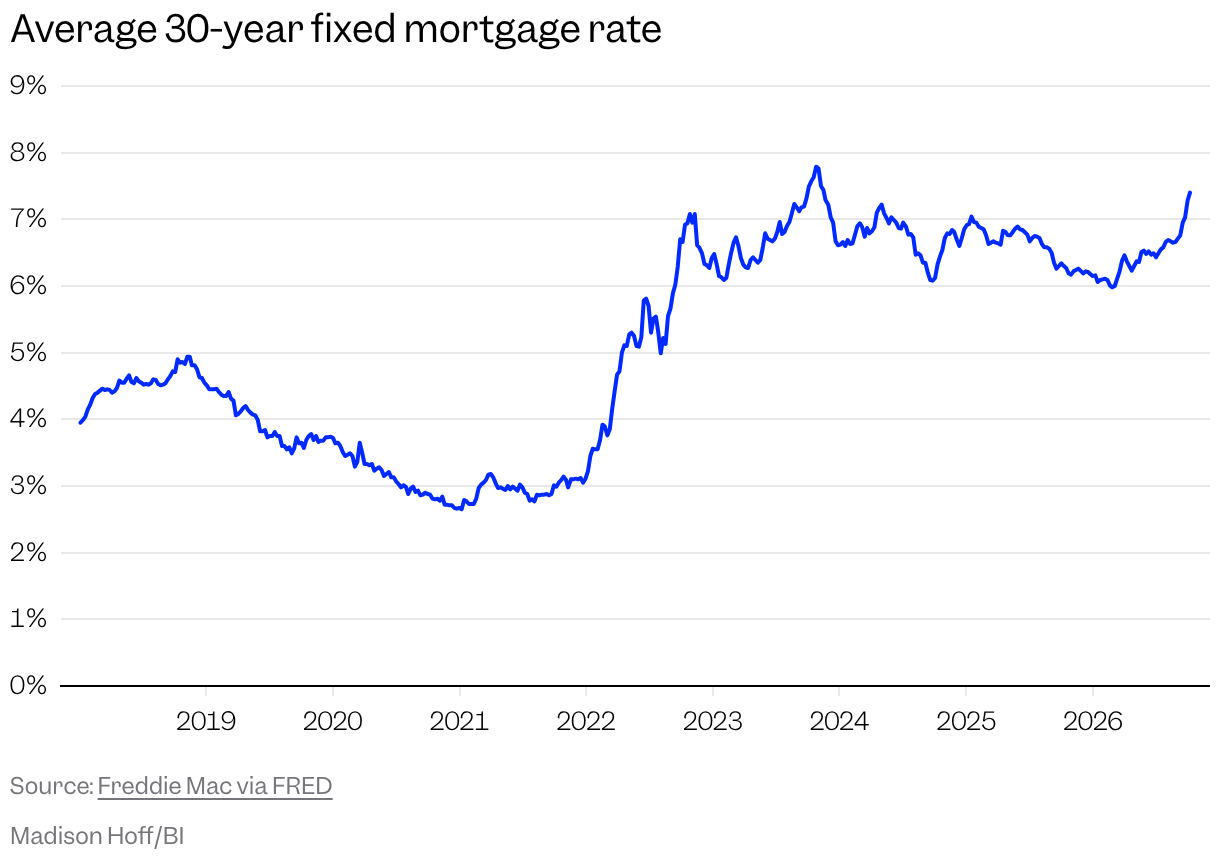
The average 30-year fixed rate was at 7.4% for the week ending October 8, making it challenging for both newcomers and homeowners looking to move. Home prices, utilities, and other homeownership-related costs have increased.
A CNBC/SurveyMonkey quarterly survey found that about a third of renters want to own a home but don’t think that will ever be possible due to affordability. Multiple factors are making it tough to purchase a place.
The Federal Reserve Bank of Atlanta tracks the household income required for homeownership. The bank defines “qualified income” to be no more than 30% of income spent on costs, including principal and interest payments, property taxes, property insurance, a 10% down payment, and private mortgage insurance.
That qualified income — what you need to actually afford a home without breaking the bank — darted away from actual median income in 2021 and remains elevated, at about 1.5 times the actual median income as of July.
“Our country, historically, if you made the median income or you made below the median income, you could still be a homebuyer,” said Domonic Purviance of the Atlanta Fed’s Supervision and Regulation Division. “Well, that’s less likely today. What’s likely to be the case is owning a home is primarily an option for higher-income households just based on where affordability is.”
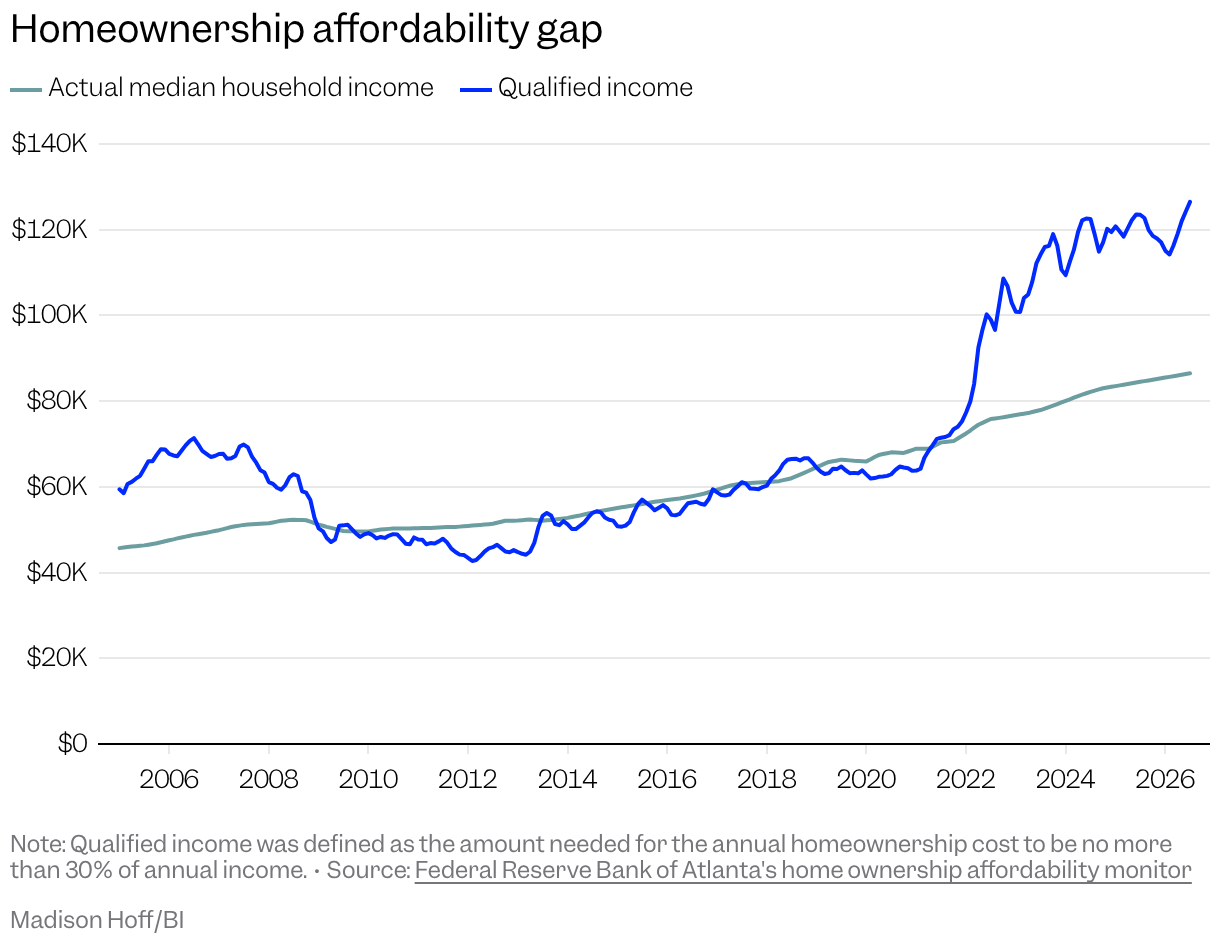
“If home prices are held constant and interest rates are held constant, and the only thing you adjusted was incomes, then incomes would have to increase by 46% in order to make housing affordable,” Purviance said, adding that the main factor behind the widening is the jump in mortgage rates over the past few months.
Given how rates have climbed since the affordability tracker’s most recent July estimate, Purviance said it’s likely the gap has increased. The average 30-year fixed mortgage rate has risen to its highest level since 2023.
Purviance said there are some housing markets, like in Austin, where home prices have softened, but not enough to make “a significant dent in the housing affordability picture.” He said people shouldn’t think they’ll buy when prices return to pre-pandemic levels, because that’s unlikely to happen.
“Really, the only thing that can really create greater affordability, at least natural market forces, is if you see interest rates adjust below their longer-term average,” he said. People who have been locked into lower rates may be more willing to sell their home if that were the case, which Purviance said could create some downward pressure on prices.
Still, people are buying; new single-family house sales increased from July to August, although existing home sales fell. Daryl Fairweather, Redfin’s chief economist, said people looking to buy might be able to find some deals as existing homeowners become more desperate to sell. Redfin’s data showed the share of active listings with a price drop in August was near the series high of 20%, although the average size of the drop is down from its level at the start of the data in 2012 — 4.1% versus 6.2%.
“Markets where there’s a lot of new construction, builders are especially eager to make deals and lower their prices and offer concessions like mortgage rate buydowns or cash at closing,” Fairweather said. “So affordability is still a huge problem, but there are ways that buyers are getting at least a slightly better deal in this market.”